

What if the smoothest EA equity curve is the one that deserves the closest audit? If you’re trying to learn how to spot fake forex ea backtests, a high win rate or impressive profit figure won’t settle the question. It may reflect a genuine strategy, flawed assumptions, curve fitting, or fabricated results. No single metric proves fraud, but missing evidence makes a backtest harder to trust.
Marketing screenshots rarely show enough to reproduce a test. You need to know which EA version, settings, historical data, date range, and trading-cost assumptions produced the results. Spread, commission, and slippage can change the picture, while parameters tuned too closely to past price movements may fail on unseen data. Even a credible backtest is historical evidence, not a promise of future performance.
This guide gives you a practical audit sequence: inspect the claims, request the files and settings needed to rerun the test, assess costs and curve-fitting risks, then move from out-of-sample testing to forward testing before considering small live deployment. Use the same checklist for any EA, including software from RobotForexPro. The goal is a more disciplined decision, based on reproducible evidence rather than a polished curve.
Key Takeaways
- Learn how to spot fake forex ea backtests by separating evidence of fabrication from overfitting, missing disclosures, and overly optimistic test assumptions.
- Recognize how curve fitting and look-ahead bias can make historical results appear stronger than performance on unseen data.
- Compare screenshots with reproducible tester reports and account records, while treating Myfxbook verification as supporting evidence rather than proof of every backtest claim.
- Use a structured audit to match the EA settings, symbol, timeframe, test dates, balance assumptions, and data before drawing conclusions.
- Weigh evidence that justifies further evaluation against unresolved warning signs, without treating any historical result or metric as a guarantee.
How to spot fake forex EA backtests: separate fraud signals from weak testing
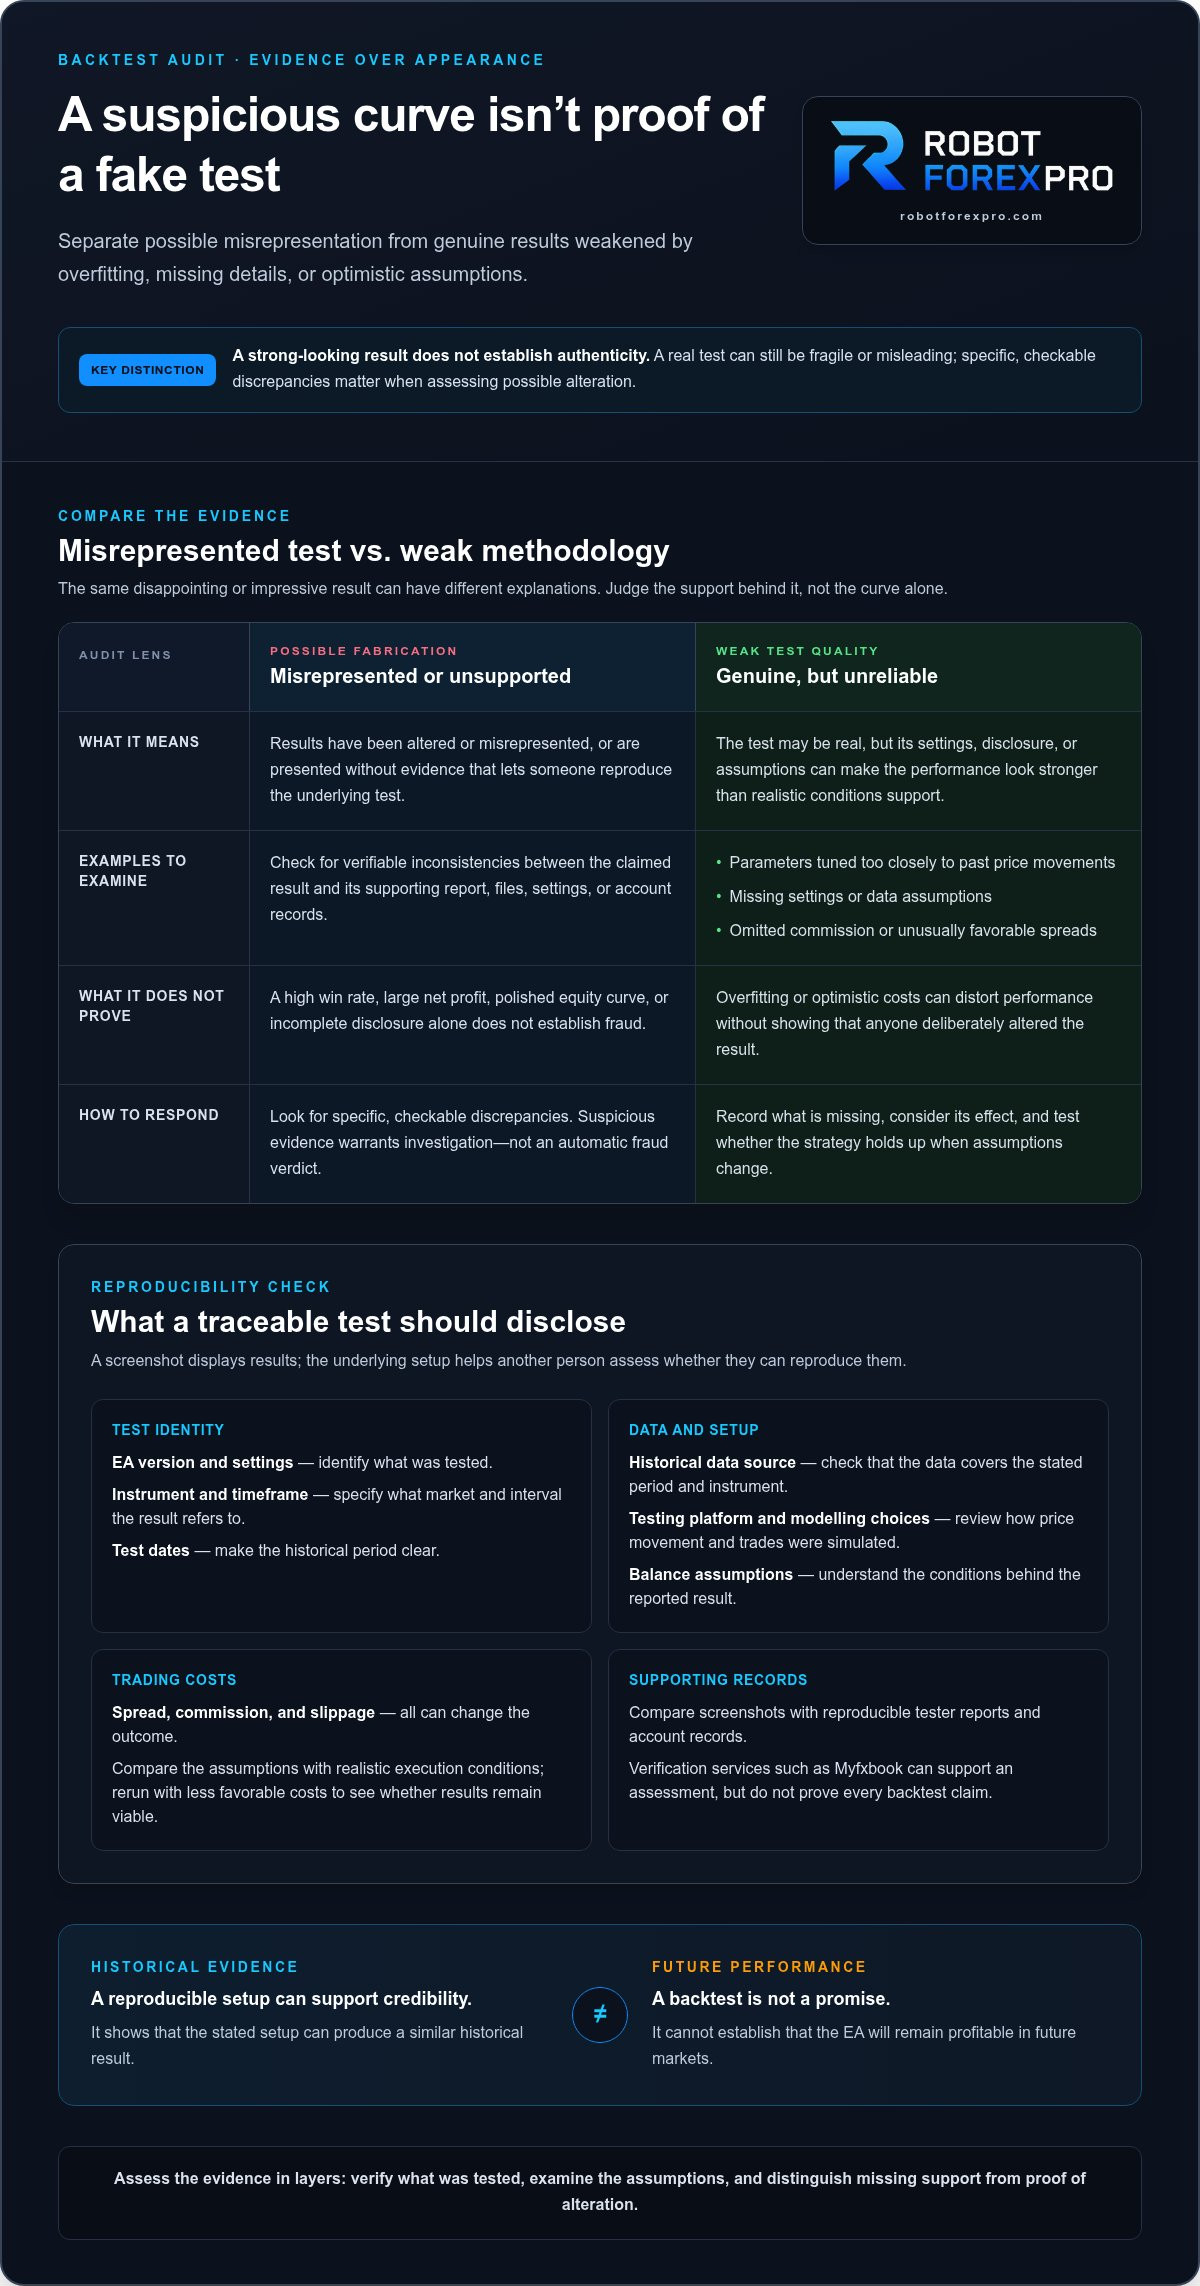
A forex EA backtest is a simulation of a trading system against historical market data. A fake backtest is a result that has been misrepresented, altered, or presented without evidence that allows its underlying test to be reproduced. That is different from a genuine test with weak methodology. A curve may be real yet depend on overfitting, incomplete disclosure, or trading assumptions that make performance look better than it would under realistic conditions.
That distinction matters. A polished equity curve, a high win rate, or a large net profit can attract attention, but none establishes whether the report is authentic. The same applies to claims about algorithmic systems. Algorithmic trading describes strategies that use algorithms to make trading decisions, but the label alone says nothing about the quality or validity of a particular EA’s test.
Suspicious evidence warrants investigation, not an automatic fraud verdict. Look for verifiable inconsistencies and missing support before drawing conclusions about a seller or a backtest.
What makes a forex EA backtest credible enough to examine?
A result is easier to assess when it identifies the test dates, instrument, timeframe, testing platform, and EA settings. The report should also make clear which balance assumptions and modelling choices were used. These details create a traceable record: another person can configure the same test and see whether the reported outcome is reasonably reproducible.
A screenshot is only a display of results. It usually can’t show the full setup or assumptions behind them. Look for enough underlying information to interpret the result, rather than treating an attractive chart as standalone evidence.
Reproduction supports credibility, but it has a clear limit. It can show that a stated setup produces a similar historical result; it can’t establish that the EA will remain profitable in future markets.
Why a weak backtest is not automatically a fake backtest
Overfitting happens when parameters are tuned excessively to match historical price movements. The resulting test may be genuine, but the strategy may have captured noise rather than a durable pattern. A performance drop on data that wasn’t used during tuning is a reason to investigate robustness, not proof that the original report was fabricated.
Incomplete disclosure also reduces confidence without proving deliberate deception. If the seller doesn’t provide the settings or data assumptions, you may not be able to verify the result. That is a transparency gap. It becomes evidence of alteration only when supported by specific, checkable discrepancies.
Cost assumptions require the same careful distinction. A test that omits commission or uses unusually favorable spreads can overstate performance. That makes its methodology optimistic and potentially misleading, but it doesn’t by itself show that someone altered the results intentionally. Record what’s missing, assess how it could affect the outcome, and avoid making an accusation without verifiable evidence.
How backtest settings and data can create misleading EA results
A backtest is only as informative as the conditions it simulates. An EA may look highly profitable when its parameters are tuned to one historical period, trades are modelled with limited price detail, or execution costs are understated. Those weaknesses can distort a result without proving it was fabricated. For anyone learning how to spot fake forex ea backtests, the key is to identify which assumptions shaped the performance and whether the strategy holds up when those assumptions change.
Test quality depends on both the data and the execution assumptions used to simulate trades. Review them together, not as isolated technical settings.
Which data and modelling choices deserve scrutiny?
Start with the symbol, timeframe, date range, and historical data source. Confirm that the data covers the period shown in the report and matches the instrument being tested. Tick-level modelling can represent more detail about price movement within a bar; simpler bar-based methods may rely on open, high, low, and close values. Neither method alone proves a result is fake, but the choice can affect how entries, exits, and stops are simulated.
A platform’s modelling-quality percentage is an indicator within that platform’s testing framework, not universal proof that the underlying data or result is reliable.
Execution costs matter, too. A strategy that enters and exits frequently can be particularly sensitive to spread, commission, and slippage. For example, a test using a fixed, unusually low spread may report better net performance than one using variable spreads and realistic slippage. Compare the assumptions with the conditions the strategy would face, then rerun the test with less favorable costs to see whether its results remain viable.
How optimization can disguise a fragile strategy
Optimization tests parameter combinations against historical data. The more aggressively settings are adjusted to maximize past performance, the greater the risk of curve fitting. Check whether the EA was evaluated on a separate out-of-sample period that wasn’t used to choose its settings. A strategy that performs well only on its optimization window may have learned historical noise rather than a repeatable trading signal.
Walk-forward testing can help expose that weakness by optimizing on one segment of history and evaluating the chosen settings on a later segment, then repeating the process across periods. Monte Carlo analysis can also stress-test outcomes by varying trade sequences or other test conditions. These methods assess robustness; neither guarantees future performance.
- Compare results across the exact symbol, timeframe, and date range tested.
- Check whether cost assumptions match the strategy’s trading frequency.
- Look for performance that survives unseen periods and reasonable variations.
Apply the same evidence checks to any EA you evaluate, including the Forex EA software from RobotForexPro. Historical results remain a starting point for analysis, not a forecast of live outcomes.
Does an impressive EA backtest prove the system works live?
No. A backtest estimates how an EA would have performed under a historical simulation. Live trading introduces actual execution conditions, including variable spreads, slippage, and changing market behavior. To judge the evidence, separate what each record can demonstrate from what it cannot. This distinction is central to how to spot fake forex ea backtests, and to avoid mistaking historical performance for proof of future results.
Backtest report versus independently tracked account
A screenshot is the weakest evidence on its own. It can display a selected result, but usually doesn’t show the full settings, test data, or assumptions needed to reproduce it. A detailed tester report is stronger because it records the test configuration and output. Reproducing it provides another check, though it still confirms a historical simulation, not live execution.
Independent account tracking and live-account records provide different evidence. They can show trades and account performance over time, but they don’t establish that a separate backtest used the same strategy or was honestly represented. Myfxbook verification can support review of account history, but it doesn’t validate every backtest claim or prove that the tracked account matches the EA and settings in a promotional report.
Compare the strategy, account, dates, instrument, and trading conditions before drawing conclusions. If a backtest covers one period and the live record covers another, treat them as separate evidence. For a practical framework for assessing exposure and risk, review forex EA drawdown and portfolio risk metrics.
Read performance metrics as a set, not a sales headline
Net profit needs context. A large gain may have come with deep drawdowns, substantial open exposure, or a small number of trades. A high win rate can also hide occasional losses large enough to offset many small wins. Check the number and distribution of trades, the size and duration of drawdowns, and whether the account used leverage or position sizes that materially affected risk.
Profit factor compares gross profit with gross loss, while the Sharpe ratio relates returns to volatility. Both can help describe performance, but neither is a pass-or-fail authenticity test. Their meaning depends on the period, data, assumptions, and calculation method. Don’t compare figures blindly across reports that use different conditions.
- Check whether profits are supported by a meaningful trade history.
- Assess drawdown and exposure alongside returns.
- Compare metrics only when the calculation basis and test conditions align.
Strategy structure also matters: frequent position increases or recovery logic can change how apparent win rates and losses should be interpreted. The guide to comparing forex EAs without martingale provides relevant context. Stronger evidence can justify further testing, but no verified account or backtest guarantees future performance.
How to audit a forex EA backtest before risking capital
Turn a performance claim into a repeatable test. This workflow helps you identify missing evidence, locate assumptions that inflate results, and decide whether an EA merits further evaluation. A failed reproduction is a warning that needs an explanation, not standalone proof of fraud.
- Request the test record. Get the full Strategy Tester report, EA version, parameter values, test dates, symbol, timeframe, platform version, and deposit assumptions. A cropped screenshot is not enough to define the test.
- Reproduce the setup. Match the symbol, timeframe, date range, starting balance, leverage assumptions, and EA parameters. Keep a copy of the report and record any settings that you can’t match exactly.
- Inspect the data and modelling. Identify the historical data source and modelling method. Check whether the available history covers the stated period and whether the chosen method can represent the EA’s trade timing and exits.
- Model execution costs. Record spread, commission, and slippage settings. Rerun the test with realistic, less favorable costs to see whether results depend on unusually optimistic assumptions.
- Test robustness. Compare performance on data excluded from optimization. Then vary execution assumptions and review whether the strategy remains coherent, rather than relying only on the best historical result.
What information should you capture to reproduce a test?
Save the platform version, instrument, timeframe, date range, deposit and balance assumptions, and every EA parameter value. Also capture Strategy Tester settings for spread, commission, slippage, and modelling. Preserve the original report and the files or inputs needed to rerun it. This record lets you trace differences to specific settings instead of relying on memory.
How to interpret mismatched results and missing details
Small differences may result from different data feeds, execution assumptions, or platform settings. Note each difference and test whether it explains the change. A large, unexplained gap between the claimed report and a correctly configured reproduction deserves closer scrutiny. If essential settings or inputs are missing, document the limitation; don’t treat missing information alone as proof of deliberate alteration.
Use demo forward testing as another observation stage after historical and out-of-sample checks. It can show how the EA behaves under current conditions, but it doesn’t remove the need for position limits, monitoring, or other risk controls. Historical and demo results can inform a decision, not guarantee future performance.
A disciplined audit is a practical way to answer how to spot fake forex ea backtests without treating every weakness as fraud. Apply the same process to any system you consider. Once you’ve assessed the evidence and its limits, explore RobotForexPro’s Forex EA software as another option for evaluation.
Make an evidence-based EA decision after checking the backtest
A backtest audit should lead to a decision, not a verdict based on one impressive chart or one imperfect result. Separate what the evidence supports from what remains uncertain. A reproducible test, clear assumptions, sensible risk measures, and performance that holds up outside the optimization period can support further evaluation. Missing details, unexplained discrepancies, or results that collapse under realistic costs leave important questions unresolved.
Keep the conclusion proportionate to the evidence. No historical test, verified track record, or performance metric guarantees that an EA will perform similarly in the future. Backtests model past conditions. Account records show past trades. Neither removes market risk or proves future profitability.
When to pause, investigate, or move on
Pause if essential settings, test dates, or execution assumptions are absent. Without them, you can’t assess what the reported result represents. Investigate when a material result fails to reproduce under the stated conditions. Check for differences in platform version, historical data, costs, or parameters before deciding what the mismatch means.
Move on if important explanations remain unsupported or the evidence can’t be assessed. That’s a practical risk decision, not proof of fraud. Avoid making public accusations unless you have verifiable evidence of deliberate misrepresentation.
Use the same checklist when evaluating any EA
Apply consistent standards across systems. Compare test transparency, strategy behavior, drawdown, trade history, and performance under realistic assumptions. Don’t relax the evidence threshold because an EA has a polished presentation or a familiar name. Use the same questions and risk criteria for every product under consideration.
That includes RobotForexPro’s EAs. RobotForexPro provides EA software for independent use; it is not a broker or managed-account operator. Apply the same evidence checklist, and don’t assume that a product’s historical results have been independently verified unless supporting evidence establishes that.
For a broader framework covering software evaluation beyond backtest claims, use the 2026 forex EA buyer’s guide. It can help structure your comparison before you make a purchase or deployment decision.
The disciplined answer to how to spot fake forex ea backtests is to verify, compare, and document, then act only on what the evidence can support. If you’re ready to review available software with those limits in mind, explore RobotForexPro Expert Advisors. Continue to assess any EA independently, and remember that no test removes the risk of loss.
Make evidence checks part of every EA decision
Use a consistent audit standard before you commit capital. Treat each purchase or deployment as a decision under uncertainty, not a search for a backtest that promises certainty. Keep a written record of what you verified, what remains unclear, and what would cause you to pause. That discipline makes it easier to compare systems objectively and revise your decision as new evidence becomes available.
Knowing how to spot fake forex ea backtests is valuable beyond identifying suspicious claims. It helps you evaluate trading software on evidence and risk rather than sales presentation. No historical result can remove the possibility of loss, so make your next step measured and informed.
RobotForexPro sells proprietary EA software for independent traders, with EAs for currency and gold trading. Explore the available options and assess them with the same standards you’d apply to any system: Explore RobotForexPro Expert Advisors.
Stay evidence-led, keep risk controls in place, and move forward only when the decision fits your own trading plan.
Frequently Asked Questions
Can you prove a forex EA backtest is fake from a screenshot alone?
No. A screenshot can be cropped, edited, or genuine, and the image alone usually can’t establish which. It also rarely shows enough context to identify the platform, test period, settings, or source data. Treat it as a claim to investigate, not proof of fabrication. Look for a complete report or original test output, then check whether the stated setup can produce comparable results.
Does a 99.9% modelling-quality result prove an MT5 backtest is reliable?
No. A 99.9% modelling-quality figure is an indicator reported within a testing process, not a universal certificate of accuracy. It doesn’t by itself establish that the underlying history is appropriate, costs are realistic, or the EA avoided look-ahead bias. Check what the platform’s figure represents, which data was used, and whether the test’s assumptions match the strategy and instrument.
Can an over-optimized EA backtest still be genuine?
Yes. The test may have been run as reported, while its settings were tuned so closely to the selected historical period that performance doesn’t carry over. For example, an EA may show a strong result with one narrow parameter combination but weaken when tested on later data. That points to possible fragility, not automatically to fabricated results. Treat out-of-sample performance as a separate question.
What does look-ahead bias mean in an EA backtest?
Look-ahead bias occurs when a simulated decision uses information that wouldn’t have been available at that point in real trading. For example, a strategy might act on a candle’s final high or close before that candle has finished forming. This can make entries appear better timed than they could be live. Review how the EA reads prices and triggers trades, especially around bar changes.
Can a profitable backtest lose money on a demo or live account?
Yes. A historical simulation can be profitable while later trading loses money. Market behavior can change, and real-time execution may differ from the model because of spreads, slippage, or order handling. Demo results can provide useful observations, but they don’t guarantee live outcomes or reproduce every live-account condition. Treat a backtest as one input in a broader evaluation, not a promise of returns.
Is a verified Myfxbook account proof that an EA backtest is genuine?
No. A verified Myfxbook profile can support review of the linked account’s trading history, but it doesn’t establish that a separate historical test used the same EA, settings, or dates. Compare the account’s instruments, trade timing, and strategy behavior with the backtest claim. If they don’t align, the account may still be real, but it doesn’t substantiate that particular test.
What should I do if an EA seller will not provide reproducible backtest details?
Pause before committing capital. Record which information is missing, such as the test period, parameter values, or modelling assumptions, and treat the result as unverifiable rather than automatically fraudulent. If the missing evidence prevents meaningful evaluation, choose not to proceed until the uncertainty is resolved. Learning how to spot fake forex ea backtests means separating a lack of proof from proof of deliberate deception.